
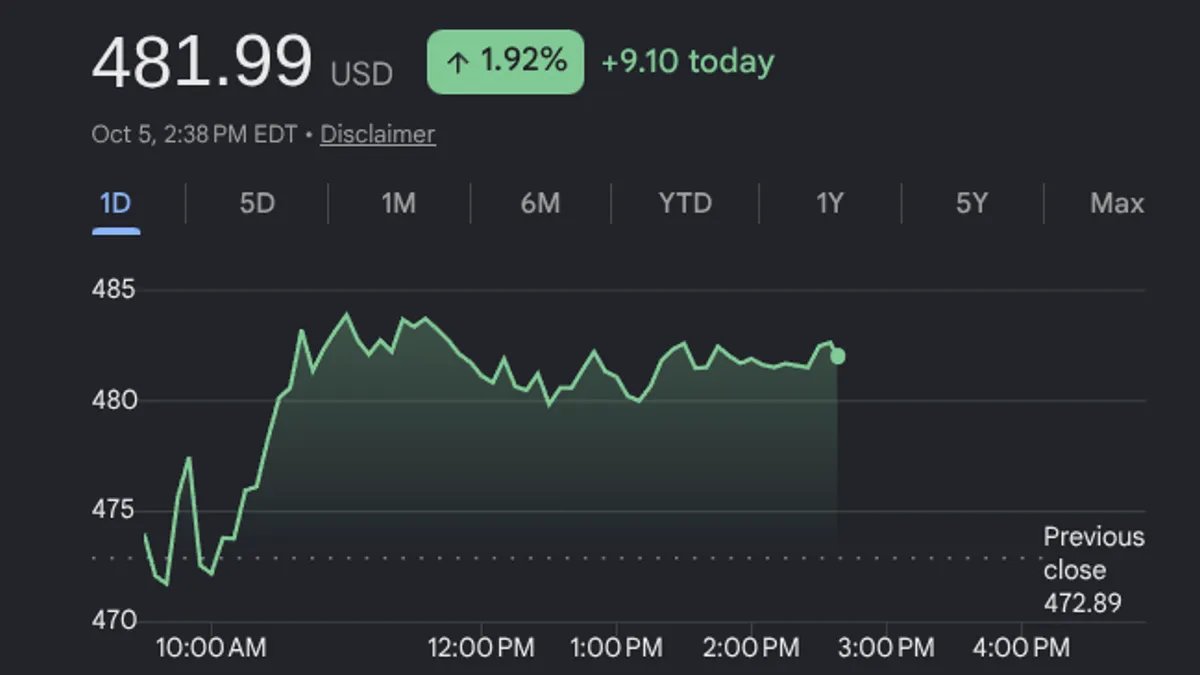

Picture Credit score: Google Finance
Spotify’s inventory is down practically 30% year-over-year, with UBS dropping its worth goal as a consequence of price pressures regardless of a typically bullish temper.
Spotify’s inventory (SPOT) has been lackluster this yr, down practically 30% year-over-year, regardless of the broader sentiment remaining bullish as the corporate pushes to diversify. Because of this, UBS softened its worth goal this week however nonetheless says “BUY,” citing price pressures for the lowered goal worth. The inventory was buying and selling at round $481 on Monday afternoon, a slight improve from that morning however nonetheless down greater than 30% over the previous yr.
UBS analyst Batya Levi studies that the corporate continues to launch diversified merchandise and options to assist extra monetization alternatives. The agency expects that Spotify will make progress towards its monetary targets and anticipates third-quarter outcomes to be largely according to administration’s outlook.
Additional, UBS expects Spotify’s premium revenues to extend by 15.2% on a international alternate impartial foundation, in comparison with 16% within the second quarter, whereas promoting income development is predicted to speed up to eight.6% on a international alternate impartial foundation as comparisons in opposition to final yr’s notably decrease podcast stock soften.
To that finish, most of the largest banks and analysts are nonetheless saying both “BUY” or “Robust Purchase,” whereas sustaining their worth targets.
Notably, the 12-month consensus worth goal sits between $593 and $617, suggesting a roughly 25% to 30% upside from early October buying and selling ranges of ~$472 to $491. That stated, forecasts range broadly, with ranges between $400 and over $720.
Latest Analyst Updates (Late Sept – Oct 2026)
| Agency | Suggestion | Value Goal | Date |
|---|---|---|---|
| KeyBanc | Obese / Purchase | $660 (lowered from $680) | Oct 1 |
| Wells Fargo | Purchase | $570 (reiterated) | Sep 30 |
| Evercore ISI | Outperform | $700 (raised from $650) | Sep 29 |
| Morgan Stanley | Purchase | $640 (reiterated) | Sep 28 |
| Financial institution of America | Purchase | $685 (maintained) | Sep 24 |
Earlier this yr, Apple Music surpassed Spotify’s U.S.-based subscriber quantity, which may clarify among the worth softness—however there are lots of shifting elements at play. Spotify reported a 14% year-over-year income development in Q2, pushed by a 16% improve in premium income following its current worth hikes. That aligns with expectations.
Barclays highlighted that Spotify’s streaming development closed the hole with main music labels, posting 14.6% development in comparison with the common of 8.3% for main music firms. Nevertheless, even with these developments, the hole stays at its widest within the final six quarters.